Support
ECB rate decision: can €100 gas prices trigger a December rate hike?
The European Central Bank is expected to leave its deposit rate at 2.50% today, but the pause comes at a less comfortable moment than the unchanged decision may suggest. European gas has reached 100 euros per megawatt-hour for the first time since 2022.
European gas reached 100 euros per megawatt-hour as LNG supply tightened ahead of winter.
Euro-area inflation accelerated to 3.8%, led by an 18.8% increase in energy prices.
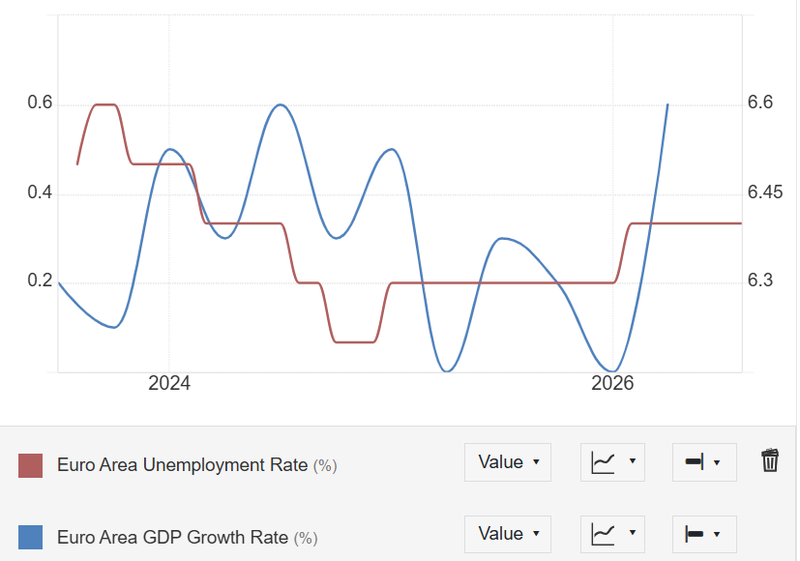
Third-quarter growth is expected to slow to 0.2%, while unemployment may remain at 6.4%.
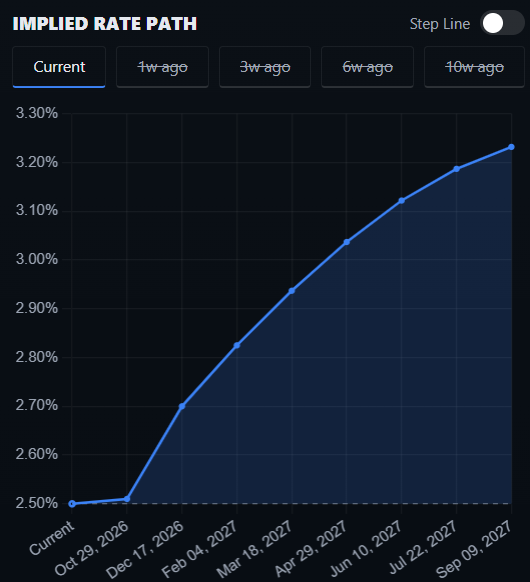
Markets are pricing a strong probability of another ECB rate increase in December.
The ECB is pausing because two forms of tightening are arriving together
The expected decision to hold rates does not suggest that the ECB is comfortable with inflation. It reflects uncertainty over how much tightening is already moving through the economy.
The ECB has raised rates twice since June, while longer-term government yields, corporate borrowing costs and bank lending standards have also moved higher. Another increase today would arrive before policymakers can separate the effects of previous decisions from the additional pressure coming from energy and bond markets.
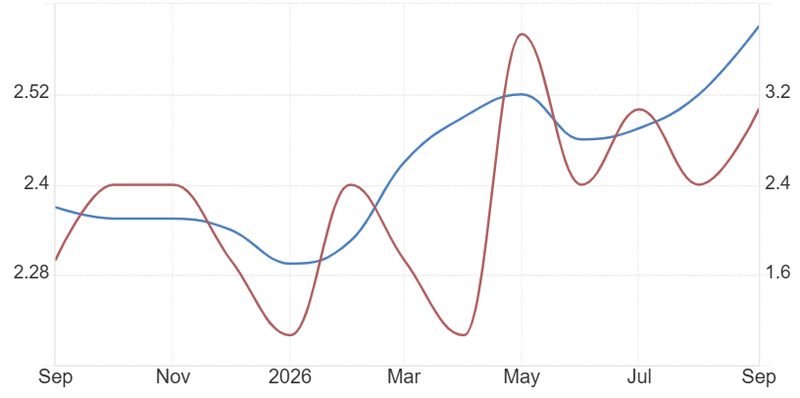
That distinction has become more important since September inflation accelerated to 3.8% from 3.2%. Energy accounted for much of the increase, but services inflation also rose to 3.2% and core inflation reached 2.5%. The figures have not yet confirmed a broad second wave of inflation, but they have made it more dangerous for the ECB to assume that the energy shock will remain isolated. The pause therefore buys information rather than relief.
Source: EUROSTAT
Gas at 100 euros could raise inflation by weakening the economy
The Dutch TTF gas benchmark briefly crossed 100 euros per megawatt-hour after disruptions to Middle Eastern LNG shipping tightened supply ahead of winter. European storage is close to 75% full, but Germany is nearer 60%, leaving the region vulnerable if colder weather accelerates withdrawals. LNG imports were also around 30% lower than a year earlier in the week ending 9 October.
The inflationary effect is already visible
Gas raises heating and electricity bills, while manufacturers face higher production costs. Industries such as chemicals, fertilizers, glass and steel may be forced to reduce output if energy costs make production uneconomic.
Europe is paying more for imported energy without producing more income in return. Household purchasing power falls, corporate margins narrow and money that could have supported consumption or investment is transferred abroad. The same shock can therefore lift inflation today and weaken demand tomorrow.
This is why 100-euro gas does not automatically make an immediate rate increase appropriate. The ECB must respond if energy begins feeding into wages, services and inflation expectations. Raising rates too early, however, could deepen the loss of demand before that pass-through becomes visible.
French bonds are tightening conditions where the economy is already vulnerable
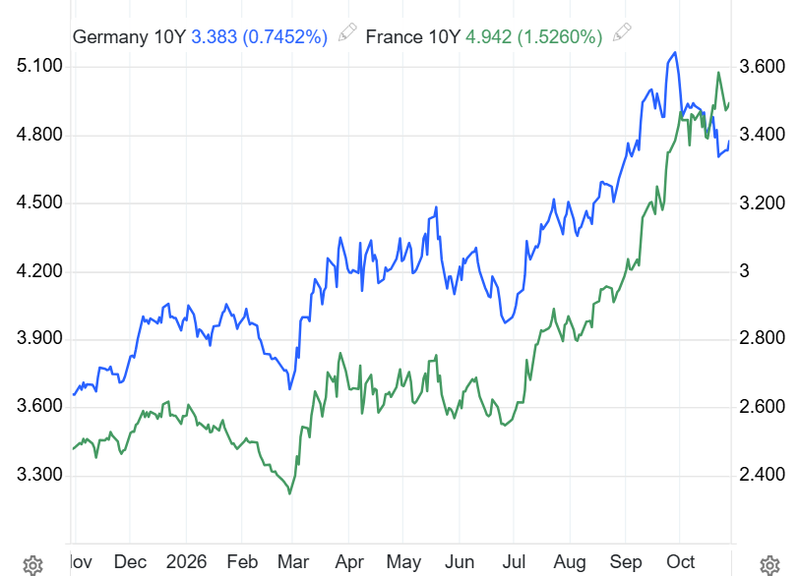
The energy shock is reaching a euro area in which borrowing conditions are no longer moving evenly. France’s 10-year yield recently crossed 5%, while its spread over German debt widened to levels associated with the sovereign-debt turmoil of the previous decade. Investors are demanding greater compensation for France’s fiscal position, political uncertainty and future borrowing requirements.
For the ECB, the significance extends beyond the French government’s interest bill. Sovereign yields influence the rates paid by banks and companies in the same country. As French debt becomes more expensive, credit can tighten for households and businesses even if the ECB leaves its deposit rate unchanged.
The ECB is therefore facing an unusual distribution of pressure
The latest ECB lending survey suggests that this process has already begun across the euro area. Banks tightened standards for corporate and consumer loans during the third quarter, while demand for business credit declined as higher rates discouraged investment. Banks expect conditions for housing and consumer lending to become more restrictive during the fourth quarter.
Gas is rising inflation across the currency union, while fiscal risk and bond-market stress are tightening financial conditions more aggressively in its weaker parts. Another rate increase would affect all members, even though some are already experiencing much more tightening than others.
Source: Trading economics
Tomorrow data will show whether the slowdown is becoming broad enough to matter
Euro-area GDP is expected to grow by 0.2% in the third quarter, down from 0.6%, while unemployment is forecast to remain at 6.4%. If those forecasts are confirmed, the economy would be slowing without producing a meaningful deterioration in employment. That would not give the ECB a clear reason to step away from December.
Companies usually reduce vacancies, investment and working hours before dismissing existing employees. Unemployment can remain low during the early stage of a slowdown, allowing wage growth and services inflation to stay firm even as headline activity weakens. A 0.2% growth rate would therefore show that restrictive financial conditions are having an effect, but stable unemployment would suggest that the labour market has not weakened enough to remove the risk of second-round inflation.
The timing also matters
Third-quarter GDP covers a period before gas moved above 100 euros and before the full effect of recent bond-market stress reached borrowers. Tomorrow’s figures will describe the economy entering the shock rather than its condition after absorbing it.
A resilient result would strengthen the case that Europe can withstand another rate increase. A weak result would suggest that the ECB is considering tighter policy just as energy costs and credit conditions begin weighing more heavily on activity.
Source: EUROSTAT
December depends on where the gas shock appears next
Markets currently expect the ECB to hold today and raise its deposit rate to 2.75% in December. By then, policymakers will have updated economic projections and more evidence on wages, inflation expectations and services prices. Money markets have priced a strong likelihood of a December increase, while economists surveyed by Reuters have also moved decisively towards another quarter-point rise.
The location of inflation will matter more than the headline number
If gas continues rising but core inflation remains contained, credit demand weakens and GDP loses momentum, the ECB could conclude that the energy shock is reducing spending before it becomes embedded in domestic prices.
If companies pass energy costs into services, workers demand compensation and inflation expectations move higher, waiting will become more expensive. A December hike would then serve as insurance against a supply shock developing into persistent inflation.
French yields could complicate either decision
The ECB may need to keep rates high enough to control inflation while remaining prepared to address disorderly bond-market fragmentation. Lowering the policy path simply to help France would damage its inflation credibility, but ignoring wider contagion could allow fiscal stress to tighten conditions across the currency union.
Source: Rate probability
The euro needs more than a hawkish ECB
Higher ECB rate expectations would normally support the euro by increasing the return available on euro-denominated assets. The currency has nevertheless fallen by around 5% against the dollar this year, while speculative investors have built their largest net short euro position in a decade.
Gas helps explain why. Higher energy prices worsen Europe’s external position because the region must spend more on imports. At the same time, weaker growth and French fiscal risk can discourage capital from entering the euro area. A December hike may improve the euro’s interest-rate support, but it would not remove the damage caused by a larger energy bill or increasingly fragmented bond markets.
The Fed also remains part of the calculation
If US data stay stronger and markets continue expecting another Fed increase, an ECB hike may prevent the rate differential from moving further against the euro without being enough to reverse the currency’s broader weakness.
A hawkish ECB accompanied by resilient GDP and contained French spreads would offer the clearest support for the euro. A hawkish message delivered into weak growth and renewed bond stress could produce only a temporary rebound, as investors focus on the economic cost of achieving lower inflation.
The pause will only be justified if it improves the December decision
Today’s decision is unlikely to settle the argument over rates. It will show which risk the ECB wants more evidence about.
Gas at 100 euros has increased the danger that inflation remains above target, but it has also reduced the amount households and companies can spend elsewhere. Higher French yields and tighter bank lending are reinforcing the second effect before the ECB raises rates again.
Tomorrow’s GDP and unemployment data will begin to show which side is gaining control. Stronger activity and a firm labour market would leave the door open for December. Weak growth combined with tightening credit would raise the risk that another increase turns an energy shock into a deeper economic slowdown.
The ECB is pausing while inflation and financial conditions tighten in different directions. The next decision will depend on whether Europe passes the energy shock into domestic prices or absorbs it through weaker demand.