
 Support
Daily discussion thread for September 21, 2026
US equities approached record highs, propelled by a technology surge, falling oil prices, and lower Treasury yields. Meanwhile, Advanced Micro Devices (AMD) achieved a landmark $1 trillion market capitalization threshold ahead of key economic events.
Nasdaq and S&P 500 near record highs propelled by robust gains across technology and artificial intelligence equities.
Oil prices drop over 3% easing inflationary concerns and pressing US 10-year Treasury yields lower.
Advanced Micro Devices achieved a historic $1 trillion market capitalization threshold for the first time.
Market participants turn their attention to upcoming Trump–Xi diplomatic talks, Middle Eastern geopolitical risks, and key central bank interest rate decisions.
US equities approach record highs amid declining oil prices and Treasury yields
US equity markets exhibited strong appreciation, led by technology firms amidst a renewed appetite for risk assets. The Nasdaq 100 Index jumped by 2.83% to 30,482 points, approaching its record high of 30,660 points. Meanwhile, the S&P 500 Index advanced by 1.49% to 7,764 points (closing near its all-time peak), whilst the Dow Jones Industrial Average gained 0.71% to settle at 52,054 points.
This solid performance was supported by lower crude oil prices, a modest decline in US Treasury yields, and robust gains across high-technology equities.
At the market close, the Brent crude futures contract (BRNX6) fell by 3.40% to $100.34 per barrel, whilst the West Texas Intermediate (WTI) futures contract (CLX6) declined by 3.82% to $92.38 per barrel. This price drop occurred despite ongoing geopolitical tensions in the Middle East, which continue to constrain energy transit through the Strait of Hormuz and the Bab el-Mandeb Strait.
Against this backdrop, the benchmark 10-year US Treasury yield declined by 4.9 basis points during today's trading session (trading at 4.95%), reflecting dampened inflationary pressures stemming from lower energy costs.
Consequently, technology equities advanced firmly on expectations that energy-driven inflationary pressures could remain contained, clearing a path for technology-related companies to deliver solid third-quarter earnings reports. Artificial intelligence-linked stocks posted considerable gains, most notably Intel (+12.14%), Advanced Micro Devices (AMD, +9.95%), and Qualcomm (+9.29%). Furthermore, Meta shares appreciated by 11.34%, whilst Tesla stock advanced by 3.03%.
However, despite the robust rally across US equity markets, several downside risks remain. Energy supply disruptions could persist or intensify if geopolitical friction in the Middle East escalates. Furthermore, a more restrictive monetary policy stance from the Federal Reserve could exert additional pressure on US sovereign debt—via higher net interest servicing costs—as well as on the broader economy.
Market participants are now turning their attention to the upcoming high-level diplomatic meeting between US President Donald Trump and Chinese President Xi Jinping scheduled for this week. Both leaders are expected to address key topics, including trade tariffs, artificial intelligence, critical minerals, and broader geopolitical developments.
AMD reaches $1 trillion market capitalization threshold for the first time
Shares in Advanced Micro Devices (AMD) reached a $1 trillion market capitalization for the first time in the company's history. The semiconductor giant benefited from today's broader market environment, in which investors drove valuations higher across US equities—particularly within the technology sector. AMD shares closed the trading session with a 9.95% gain to reach $615.52 per share. This strong performance capped an approximate monthly appreciation of 29%, extending a five-day rally.
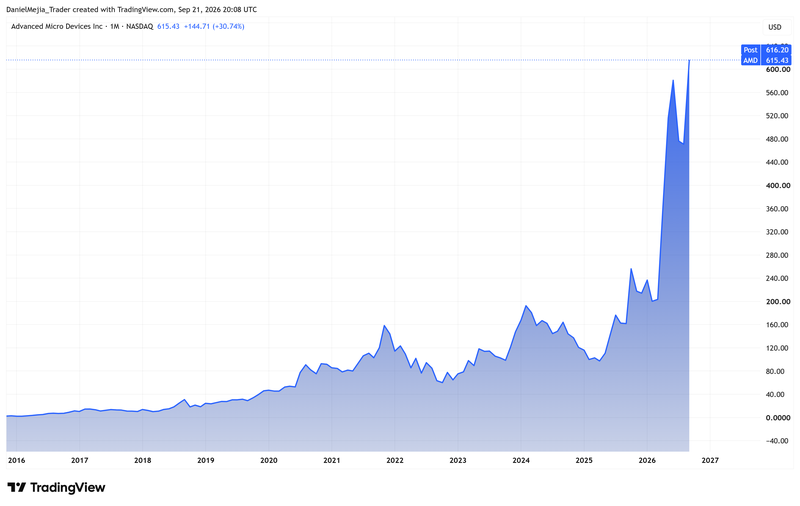
Figure 1. Advanced Micro Devices Shares (2016–2026). Source: Data from the Nasdaq Exchange; chart obtained via TradingView.
Key economic events this week
Several critical economic indicators and policy announcements are scheduled for release this week, with the following of particular importance to market participants:
Tuesday
- Mexico: Retail Sales
Wednesday
- Germany: S&P Global Manufacturing PMI
- United Kingdom: S&P Global Manufacturing PMI
- United Kingdom: S&P Global Services PMI
- US: EIA Crude Oil Stocks Change
Thursday
- Germany: Ifo Business Climate
- Switzerland: SNB Interest Rate Decision
- Mexico: Banxico Interest Rate Decision
Friday
- Germany: GfK Consumer Confidence
- US: Durable Goods Orders
