
 Support
Oil prices plunge on US-Iran talk hopes; US manufacturing activity strengthens
Oil prices declined sharply following signals of potential US–Iran diplomatic talks, while the US manufacturing Purchasing Managers' Index (PMI) exceeded expectations, driven by robust demand across artificial intelligence (AI) infrastructure.
Brent and WTI crude fell by over 7% as prospects of US–Iran peace talks eased supply concerns.
The US ISM Manufacturing PMI rose to 55.5, led by expansion in production and inventories.
The S&P 500 and Nasdaq dropped amid AI investment concerns, whereas the Dow Jones Industrial Average advanced slightly.
Market participants are turning their focus towards upcoming US Bureau of Labor Statistics (BLS) employment data, the US mid-term elections, and third-quarter corporate earnings.
Date: 3 November 2026 (GMT+3)
Oil prices plunge amid potential resumption of US–Iran diplomatic talks
Crude oil prices dropped sharply following indications of potential talks between the United States and Iran to resume diplomatic relations.
In this context, Iranian President Masoud Pezeshkian stated that Supreme Leader Ayatollah Mojtaba Khamenei had granted the government certain authorities for peace talks. Furthermore, President Pezeshkian affirmed that Tehran would seek to resolve the conflict through dialogue. Meanwhile, US President Donald Trump remarked that Iran wished to reach a deal to end the war and that "an agreement could happen", as reported by Reuters.
These diplomatic developments contrast sharply with earlier declarations pointing towards conflict escalation. In recent weeks, the US President had indicated that Washington might resume military hostilities within Iranian territory following the mid-term elections. Concurrently, Iranian forces had targeted commercial vessels and crude oil tankers in the Strait of Hormuz, maintaining a heightened climate of instability that drove oil prices upwards as energy traders remained apprehensive about further supply disruptions across the region.
At market close, the Brent crude futures contract (BRN) plunged by 7.66% to settle at $104.78 per barrel, whilst the West Texas Intermediate (WTI) futures contract (CL) fell by 7.35% to $96.44 per barrel.
US manufacturing PMI expands beyond analysts' expectations
Data published by the Institute for Supply Management (ISM) revealed that the US manufacturing PMI rose from 54.5 in September to 55.5 points in October, comfortably surpassing analysts' consensus estimates of 54.6 points. Consequently, the latest PMI reading reinforces an upward trajectory observed over the past three years, extending a ten-month period in expansionary territory as the indicator has remained above the 50.0 threshold.
Notably, the ISM report highlighted a significant acceleration in the Production Index, which advanced from 56.7 to 59.0 points, driven by robust performance across Computer & Electronic Products, Transportation Equipment, Machinery, and Chemical Products. Furthermore, the Inventories Index moved out of contraction territory, rising from 48.6 to an expansionary 51.4 points, supported by solid activity in Food, Beverage & Tobacco Products, Transportation Equipment, and Machinery.
Overall, the majority of sub-indexes pointed to expansion, although the Customers' Inventories Index continued to signal contraction.
Against this backdrop, the PMI report indicated that manufacturing output remained resilient amidst strong demand in artificial intelligence (AI), data centres, semiconductors, and infrastructure, as cited by Trading Economics.
Nevertheless, despite solid manufacturing performance, major US equity benchmarks declined broadly as concerns surrounding capital expenditure on AI, ongoing geopolitical instability, and a potentially restrictive monetary policy stance by the Federal Reserve continued to weigh on market sentiment. The S&P 500 Index dropped by 0.51% to 7,541 points, while the Nasdaq 100 Index fell by 1.39% to 27,989 points. Conversely, the Dow Jones Industrial Average rose by 0.41% to close at 51,989 points.
Market participants may shift their focus towards the upcoming US mid-term elections and key labour market data scheduled for release throughout the week by the Bureau of Labor Statistics (BLS).
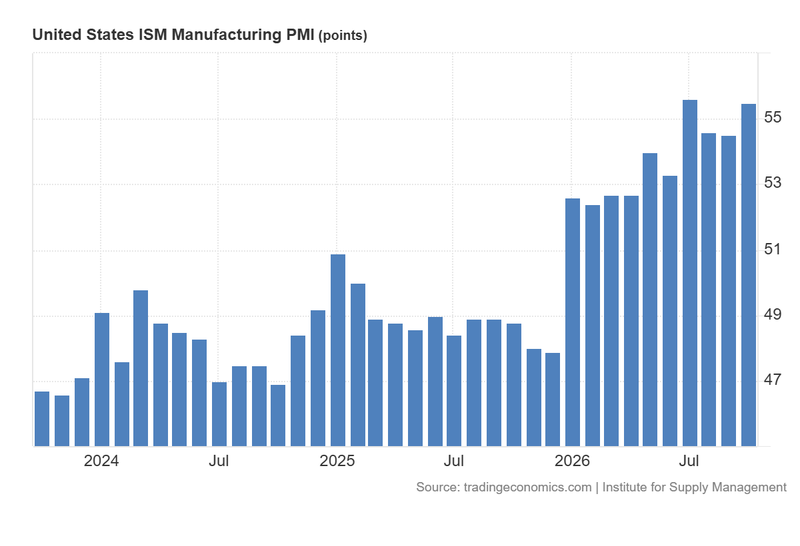
Figure 1. US Manufacturing PMI (2023–2026). Source: Data from the Institute for Supply Management (ISM); chart retrieved via Trading Economics.
Quarterly US financial results
The third-quarter 2026 earnings season continues this week. The following major corporations are scheduled to report, which may contribute to heightened volatility across US equity markets:
Tuesday
- Apple Inc (AAPL)
- Palantir Technologies (PLTR)
Tuesday
- Advanced Micro Devices (AMD)
- Amgen Inc. (AMGN)
- Pfizer Inc. (PFE)
Wednesday
- McDonald's (MCD)
- Qualcomm (QCOM)
- Uber Technologies (UBER)
Thursday
- Airbnb Inc. (ABNB)
Friday
- Moderna Inc. (MRNA)
Key economic events this week
Several critical economic indicators and central bank policy announcements are scheduled for release this week. It is possible that market participants will be monitoring the following releases:
Monday
- US: ISM Manufacturing PMI
Tuesday
- Australia: RBA Interest Rate Decision
- US: JOLTs Job Openings
Wednesday
- European Union: Inflation Rate
- Australia: Balance of Trade
- US: ISM Services PMI
- US: ADP Employment Change
- US: EIA Crude Oil Stocks Change
Thursday
- United Kingdom: BoE Interest Rate Decision
Friday
- US: Non Farm Payrolls
- US: Unemployment Rate
- US: Michigan Consumer Sentiment
- Canada: Unemployment Rate
